Bond Discount Amortization: Interest Entry and Carrying Amount (Straight-Line)
Автор: Accounting Rescue with Lisa
Загружено: 2026-11-01
Просмотров: 21
Описание:
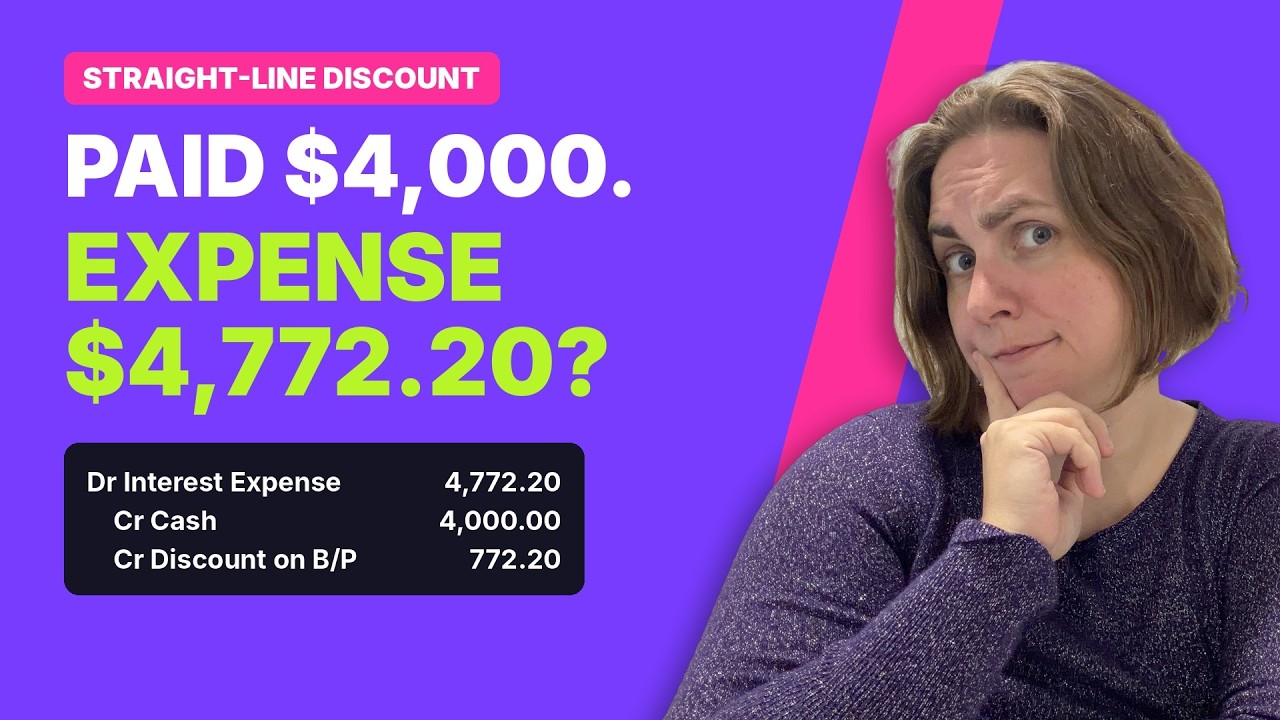
Why is interest expense higher than the cash coupon on a discount bond? This worked example records the semiannual interest entry for Night Owl Prints' $100,000, five-year bonds issued for $92,278, then updates the carrying amount as the discount is amortized.
Using straight-line amortization, we spread the $7,722 discount evenly over 10 semiannual periods ($772.20 each) and separate the three numbers students tend to mix up: the $4,000 cash coupon, the $772.20 of discount amortization and the $4,772.20 of interest expense. We record the entry (debit Interest Expense $4,772.20, credit Cash $4,000, credit Discount on Bonds Payable $772.20), update the carrying amount after period one ($93,050.20) and period two ($93,822.40), and check the total borrowing cost over the life of the bonds ($47,722).
We close with when straight-line is acceptable under U.S. GAAP and why the effective interest method is required when the difference is material.
Chapters:
00:00 Why is expense higher than the coupon?
00:11 The bond terms and issue price
00:33 Spreading the discount over 10 periods
01:05 Cash paid vs. amortization vs. expense
02:01 Recording the first interest entry
02:35 Updating the carrying amount
03:12 Period two: same entry
03:45 Why the carrying amount rises
04:03 Total borrowing cost over the bond's life
04:45 Straight-line vs. effective interest
Grab my free Accounting Rescue resources: https://accountingrescue.thinkific.co...
Taught by Lisa Habash, CPA | Adjunct Accounting Professor
Subscribe for more Accounting 1 help: / @accountingrescue
#accounting #bondspayable
Повторяем попытку...
Доступные форматы для скачивания:
Скачать видео
-
Информация по загрузке: